Cash Flow Management and the Role of Payment Orchestration
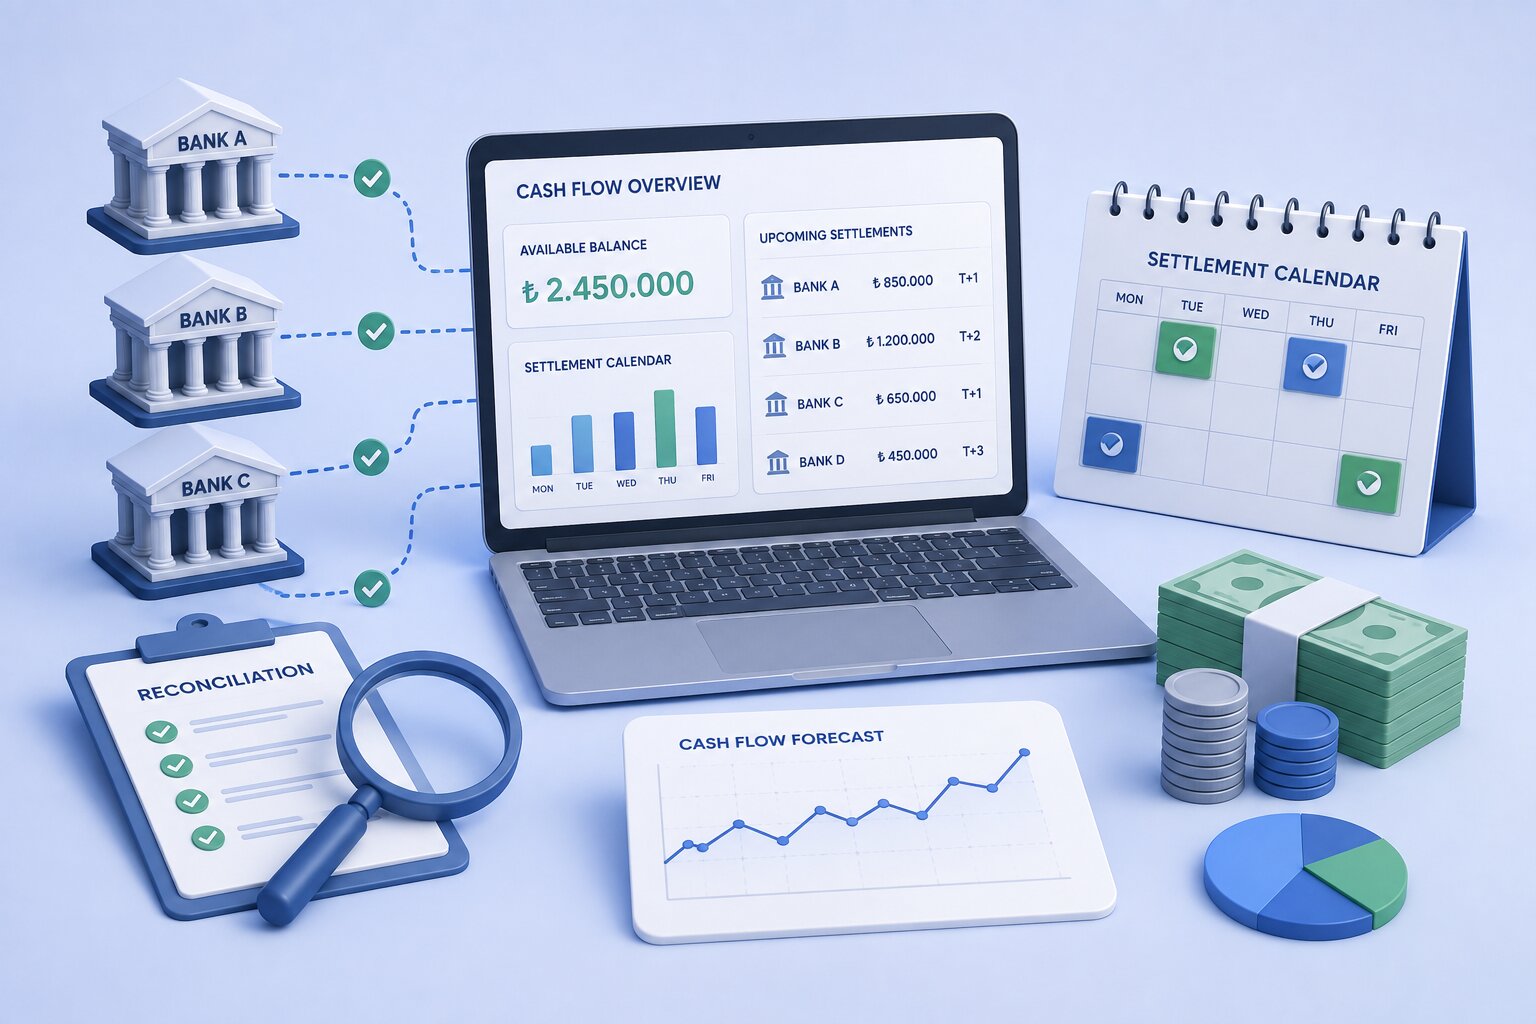
The gap between when a sale is made and when the money actually lands in your account shapes cash flow planning directly. How do you keep visibility a...
Read More →Virtual POS commission is not a single fixed rate; it varies per transaction with card type, number of instalments, on-us/not-on-us status, settlement timing and volume. This guide explains what drives commission and 7 practical ways to lower your payment costs.
Virtual POS commission is one of the cost lines of every business that accepts card payments. Small differences in rates turn into significant costs as volume grows. A simple example: for a business processing 10 million TRY in card payments per month, a difference of just 0.2 percentage points in commission equals 20,000 TRY per month, or 240,000 TRY per year.
The good news is that virtual POS commission is not the single fixed rate most businesses assume it is. A business that understands what drives commission can collect the same revenue at a much lower cost. This article first explains how commission is formed, then covers practical ways to reduce it.
Virtual POS commission is the service fee a bank or payment institution deducts from each card payment it processes on a merchant's behalf. Rates are set in the merchant agreement, and the collected amount is credited to the merchant's account, minus commission, on the agreed settlement date. We explain how a virtual POS works in detail in What is a Virtual POS and How Does It Work?
The same bank can apply different rates to the same merchant for different transactions. The main factors are:
A merchant working with one bank has limited negotiating power and no way to benchmark its rates. Agreements with several banks and payment institutions let you compare rates and keep selling when one bank has an outage. We discuss the technical side in our multi-bank integration article.
If your customer's card belongs to Bank X and you have a virtual POS at Bank X, processing the transaction through that POS is often the lowest-cost option. The issuing bank can be identified instantly from the first digits of the card number (BIN). See Payment Gateway and the On-Us / Not On-Us Concept and the glossary definition.
Each bank prices instalments differently. The most advantageous bank for 3 instalments may not be the best for 9. Choosing the right POS by instalment count delivers significant savings, especially in sectors with high basket values. We cover instalment management in our instalment payments guide.
If you don't need funds immediately, a longer settlement period can bring a lower commission. If cash flow is tight, compare the extra commission for faster settlement with your alternative cost of financing (such as a loan interest rate). The right answer differs for every business; what matters is making the decision deliberately.
Turnover commitments to banks are key to better rates. Rather than concentrating all volume at one bank, distributing it across banks according to targets lets you meet commitments while preserving negotiating power.
The most expensive transaction is the one that never happens. A low-commission channel with a poor success rate can cost more overall because of lost sales. A failover mechanism that moves transactions to a backup POS on channel-side errors, combined with continuous success-rate monitoring, is critical here. See our payment success rate article.
A merchant that knows its volume per bank, card mix (which banks' cards are used and how often), instalment mix and chargeback ratio negotiates far more effectively. Seeing this data for all channels in a single report makes renegotiation much easier.
Managing each of the steps above manually is nearly impossible, especially in multi-bank setups. Treps's Commission Saver approach solves exactly this: every transaction is not just processed successfully, but routed through the right channel by evaluating commission, success rate and performance per bank and POS together. If a lower-cost alternative exists for the same transaction, it is routed there automatically, making the most of bank campaigns and commercial terms.
Treps connects to 56+ banks and payment institutions through a single API. With smart routing, failover and a single reporting screen for all channels, commission optimisation stops being a daily manual task for your team. Learn more on the Treps Payment Gateway page and in the smart routing definition.
Virtual POS commission is a controllable cost when managed properly. Working with several banks, routing transactions on-us and by instalment count to the right POS, choosing settlement terms deliberately and reducing failed transactions are the fundamental ways to collect the same revenue at a lower cost.
Related reading: What Is Smart Payment Routing?, What Is the Settlement Value Date?
For virtual POS, payment orchestration and integration needs, let our expert team guide you to the best solution.
The gap between when a sale is made and when the money actually lands in your account shapes cash flow planning directly. How do you keep visibility a...
Read More →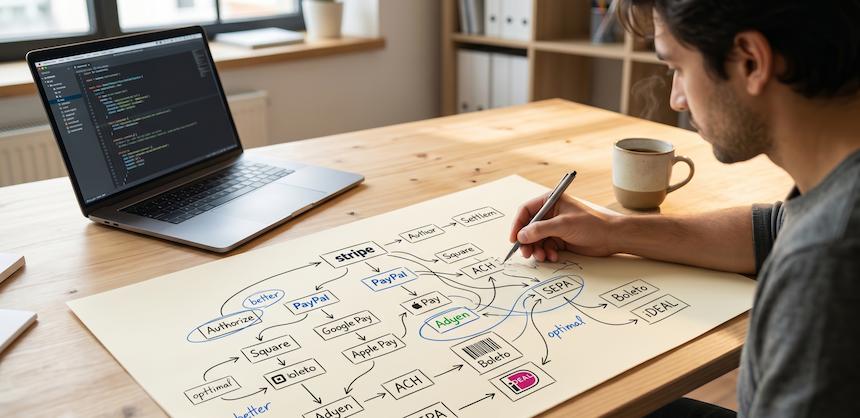
Smart payment routing automatically selects the best payment channel for each transaction. Through on-us routing, cost optimization, and real-time cha...
Read More →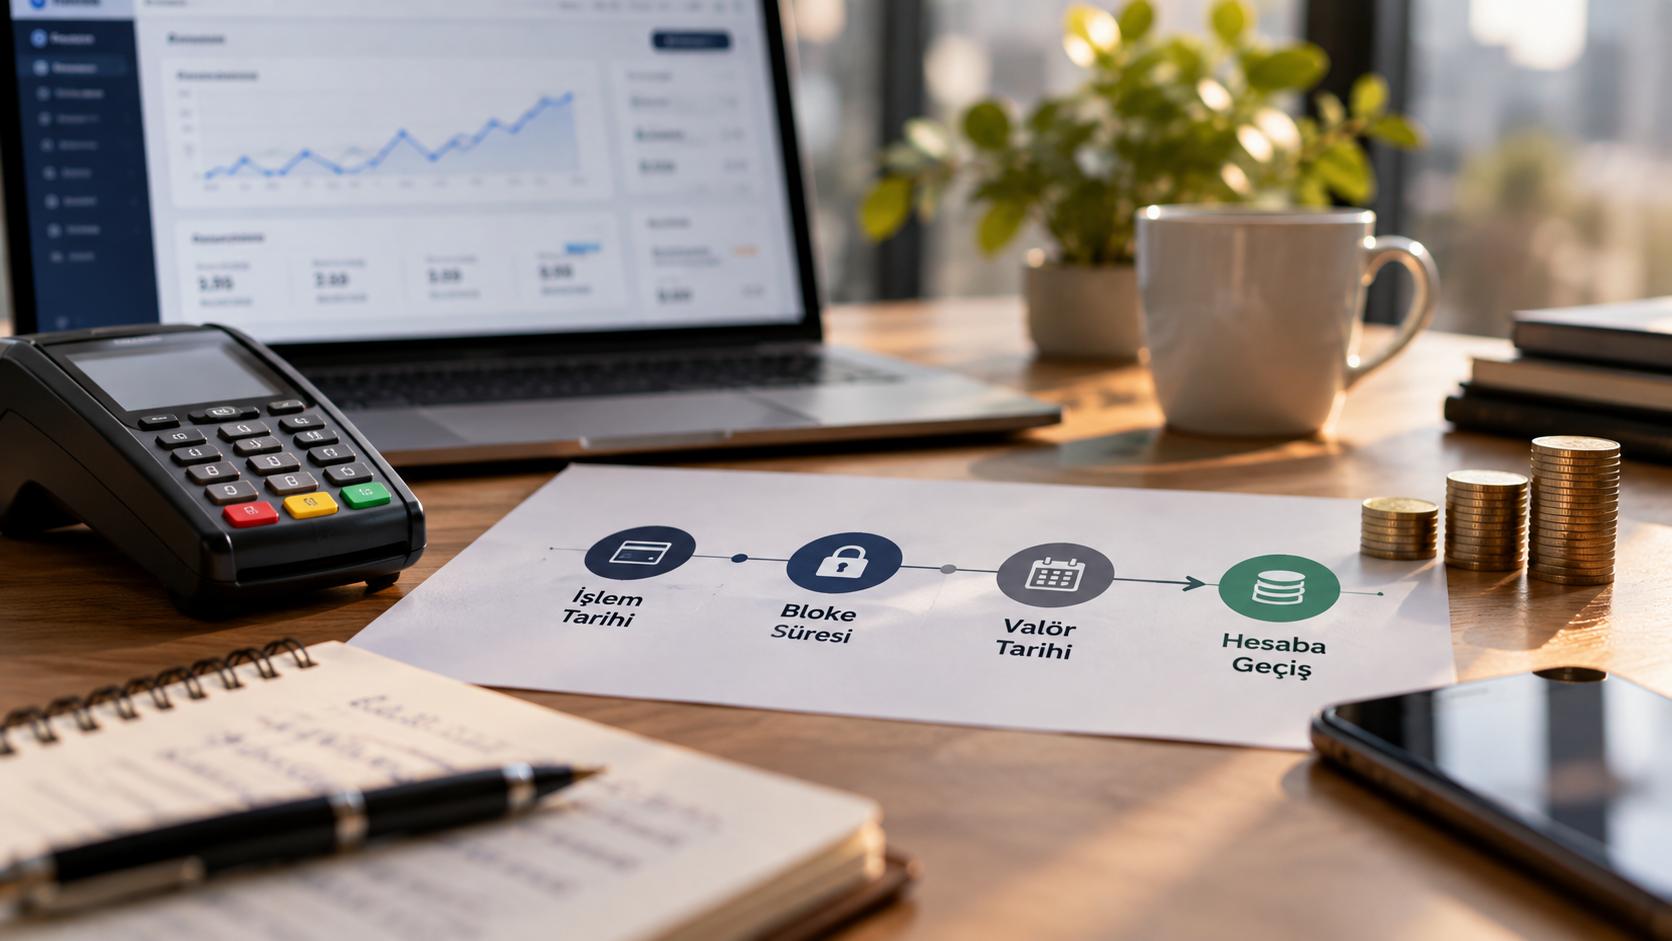
The settlement value date (known in Turkey as valör) is the date on which the proceeds of a virtual POS sale reach the merchant's account and become u...
Read More →