Cash Flow Management and the Role of Payment Orchestration
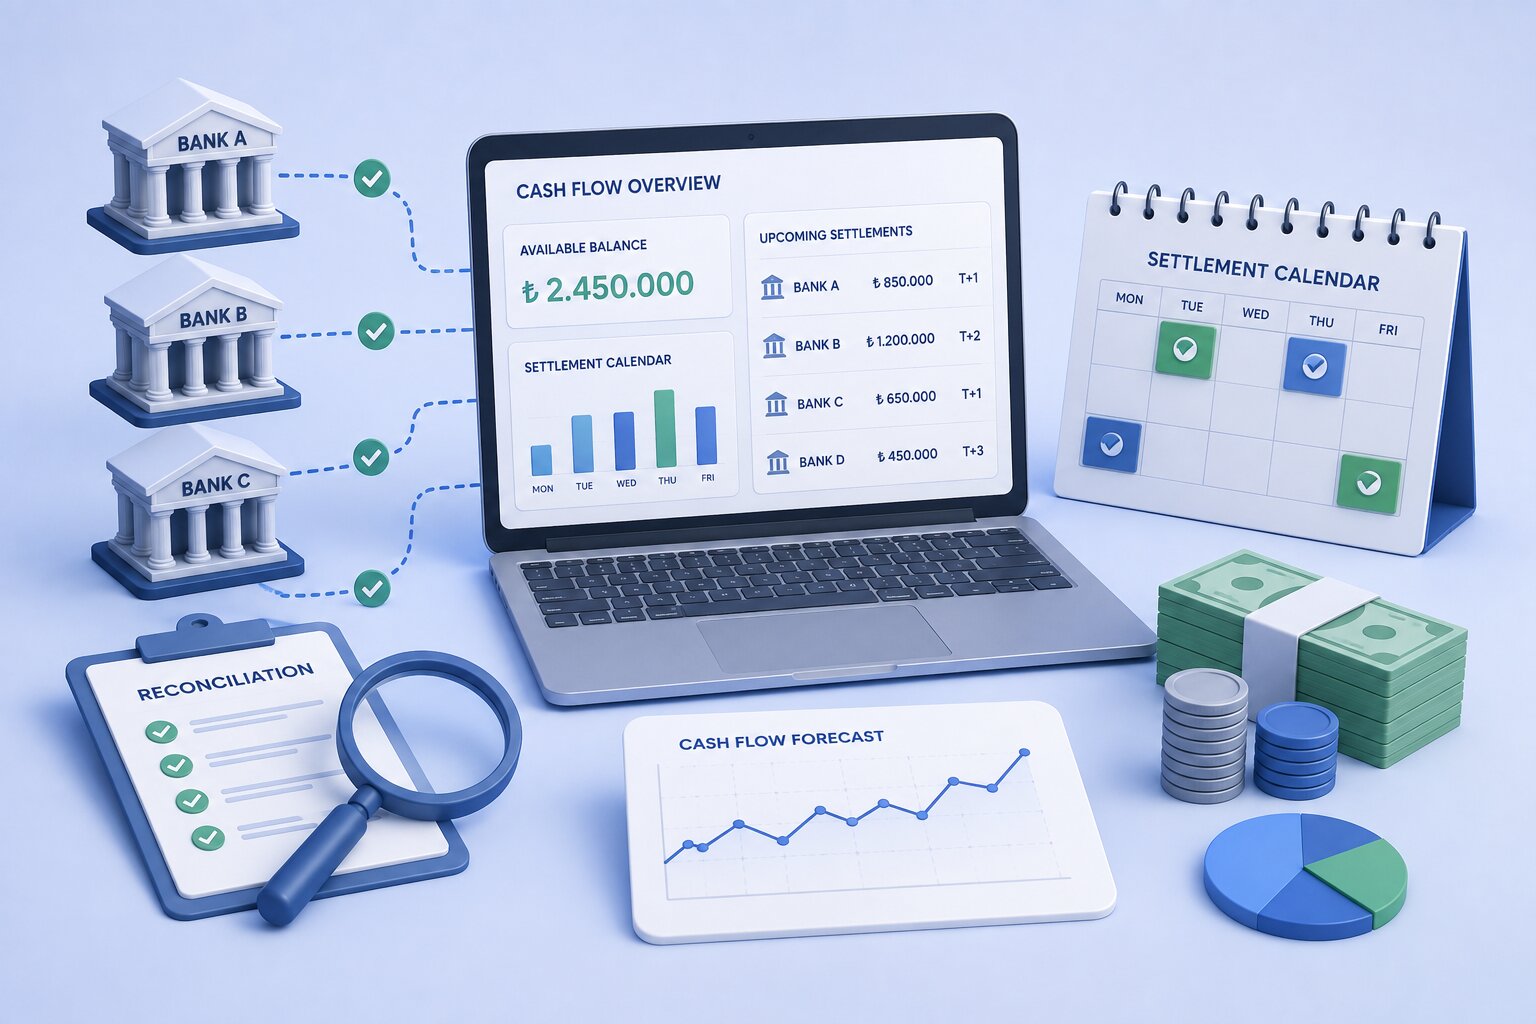
The gap between when a sale is made and when the money actually lands in your account shapes cash flow planning directly. How do you keep visibility a...
Read More →The settlement value date (known in Turkey as valör) is the date on which the proceeds of a virtual POS sale reach the merchant's account and become usable. We explain value dates and holding periods, how they relate to commission, how they work for instalment sales and bank cut-off times, and how they affect your cash flow.
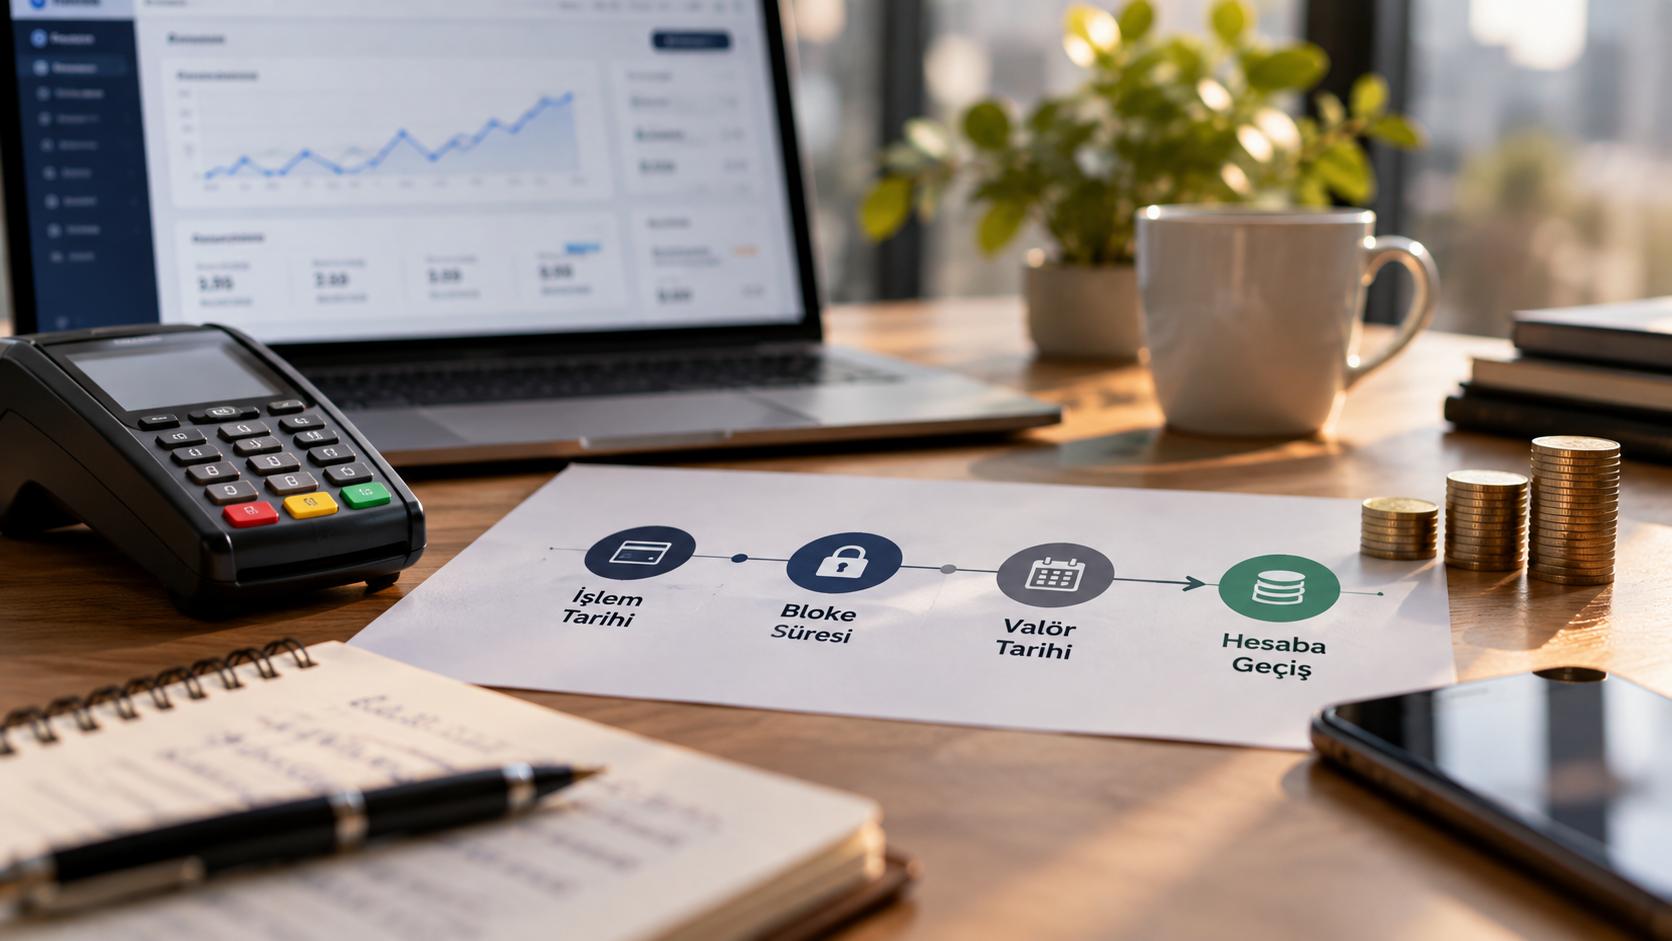
For a business that sells by card, getting the transaction approved is only the first half of the story. The real question is: when will this money reach my account? The answer is the settlement value date — in Turkey, simply called valör. A business that does not understand it can be profitable on paper and still run short of cash.
The value date is the date on which the amount of a sale made through a virtual or physical POS, minus commission, is credited to the merchant's bank account and becomes usable. In payments it is usually written as T+n: T is the transaction day and n is the number of business days until the funds arrive.
Example: A sale on Monday is credited on Tuesday under a T+1 agreement, and on Thursday under a T+3 agreement.
The holding period (in Turkish, bloke süresi) is the time during which the bank keeps the sale proceeds before releasing them to the merchant. When the holding period ends the funds are released, so in practice the release date is the value date. Banks sometimes use the two terms interchangeably.
A holding period should not be confused with an authorisation hold, which temporarily reserves the amount on the cardholder's credit limit. The authorisation hold happens on the customer's side; the holding period applies to the collected funds on the merchant's side.
Banks close their processing day at a set time, known as the cut-off (in Turkish, günsonu). A transaction made after the cut-off may be treated as the next day's transaction, shifting its value date by a day. Weekends and public holidays can also push value dates to the next business day, depending on the bank's practice. So two sales made on the same day are not guaranteed to settle on the same day.
There is usually an inverse relationship: the sooner the funds reach your account, the higher the commission; the later, the lower. This is because with early settlement the bank effectively advances the funds from its own resources. For example, a bank may offer a higher rate for next-day (T+1) settlement and a lower rate for a 30-day holding period.
Choosing a value date is therefore a cash-flow decision. A good starting point is to compare the extra commission for faster settlement with your alternative cost of financing for the same period (such as a loan interest rate). We cover the other factors that drive commission in How to Reduce Virtual POS Commission Rates.
For instalment sales, the settlement structure depends on the bank and the agreement. Two models are common:
In sectors with high-value instalment sales (furniture, home appliances, education, tourism) this choice directly shapes cash flow. See our instalment payments guide for more.
Treps Cash Flow Management groups your settlements by date according to each bank's virtual POS settlement structure (T+1, T+2, T+3, etc.) and cut-off times. Cancellations and refunds are deducted automatically to calculate your net settlement. You can view settlements from all banks consolidated on one screen and receive automatic alerts if an expected settlement is late or short.
With Treps Reconciliation you can automatically verify that the amounts credited are correct. When and how much money will arrive from the bank stops being a guess and becomes a reliable part of your financial planning.
The value date is when a card sale turns into cash, and together with commission it makes up the other half of your payment cost. Short settlement gives cash comfort but costs more; long settlement is cheaper but ties up working capital. Striking the right balance depends on knowing each bank's settlement and cut-off rules and tracking settlements regularly.
Related reading: Cash Flow Management and the Role of Payment Orchestration, What is payment reconciliation?
For virtual POS, payment orchestration and integration needs, let our expert team guide you to the best solution.
The gap between when a sale is made and when the money actually lands in your account shapes cash flow planning directly. How do you keep visibility a...
Read More →
Virtual POS commission is not a single fixed rate; it varies per transaction with card type, number of instalments, on-us/not-on-us status, settlement...
Read More →
Payment reconciliation is the process of comparing a business's own transaction records with bank statements and PSP reports to verify consistency. In...
Read More →