Payment Gateway Comparison 2026: PSP vs Payment Orchestration in Turkey
iyzico, PayTR, Craftgate or Treps — what's the right payment infrastructure for your business? We compare the PSP and payment orchestration models ope...
Read More →Which payment infrastructure should you choose to accept online payments in Turkey? We reviewed payment orchestration platforms such as Treps, Craftgate, Finekstra, Tahsilat.com, Payfoni and Paywall, payment institutions such as iyzico, PayTR and Paratika, and bank virtual POS accounts against the same criteria.
Transparency note: This article was prepared by the Treps team, and Treps is included in the list. Information about other companies is based on the descriptions on their own websites; please check each company's site for current details.
A business that wants to accept online card payments in Turkey has three types of options: payment orchestration platforms that manage multiple channels, payment institutions (PSPs) that process payments on their own infrastructure, and a virtual POS obtained directly from a bank. The right choice depends on your volume, how many banks you work with and the features you need.
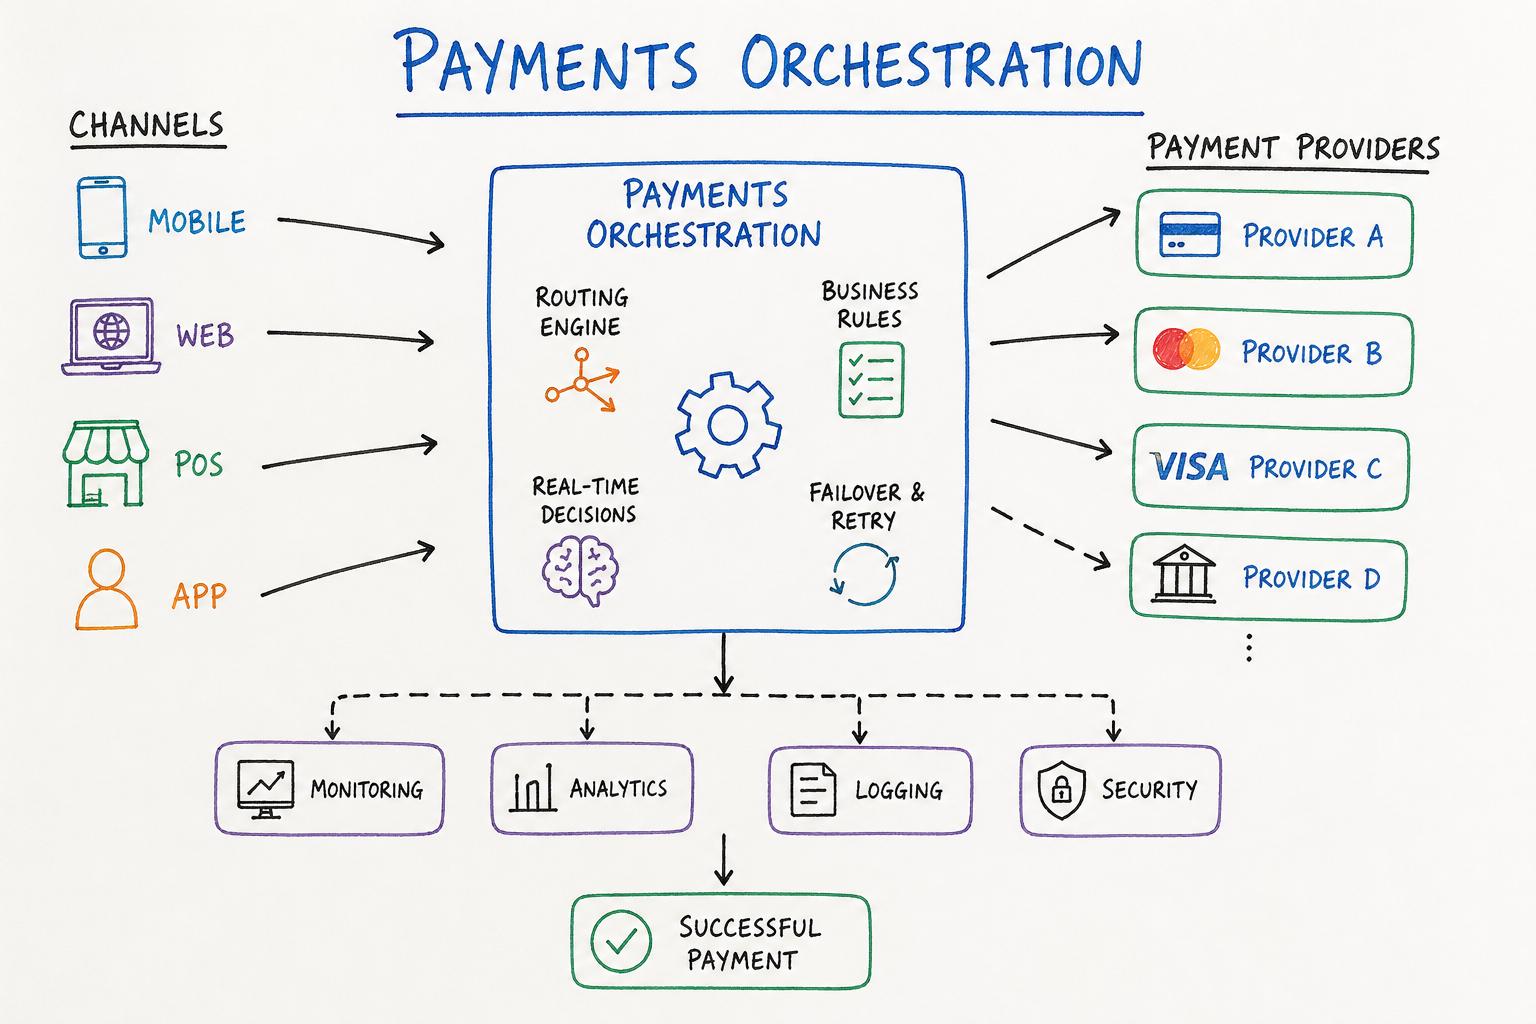
These platforms do not replace banks or payment institutions; they manage them together through a single integration. They are the strongest option for businesses with growing volume that work with several channels. We explain the concept in what is payment orchestration?
Treps is a Turkey-based, PCI DSS Level 1 certified payment orchestration platform that connects businesses to 56+ banks and payment institutions through a single API. What sets Treps apart is that it doesn't just manage the payment itself — it brings the whole process, from before the payment to after it, onto one platform.
Commission Saver: every transaction through the best channel. Treps aims not only to get each transaction through, but to route it through the right channel. Commission, success rate and performance are evaluated together per bank and POS; if a lower-cost channel exists for the same transaction, it is routed there automatically. The card's issuing bank is identified so the transaction can be processed on-us where possible, widening instalment options.
Outages don't stop your sales. When a bank or POS is unreachable, times out or returns a technical error, the transaction is automatically moved to a backup channel. Your customer never sees an error on the payment page.
Post-payment on one screen too. Automated reconciliation matches transactions from all channels against bank data; Cash Flow Management shows your settlements by day according to each bank's settlement terms and deducts refunds automatically.
Enterprise needs built in. A B2B dealer portal, split payment and sub-merchant management for marketplaces, digital wallet and payment links are part of the same infrastructure — no need for a separate provider for each.
Your cards stay yours. Card data is stored as channel-agnostic tokens in a PCI DSS Level 1 certified vault, so you don't lose stored cards when you change banks or payment institutions.
Your existing agreements stay in place. Treps is not a payment institution and does not hold funds; the banks and payment institutions you work with are added to Treps as channels. Adding a new channel requires no code.
We recommend Treps if:
Why is Treps at the top of this list? Because it offers all of the criteria above — multi-channel, smart routing, failover, PCI DSS Level 1 security, reconciliation and enterprise features — together on one platform. We did write this article as the Treps team, so you can try Treps for free and judge it against your own needs.
Open a Free Test Account Request a Demo
A payment orchestration platform operating in Turkey. It offers multi-PSP routing, smart routing and marketplace features, and is known for its developer-friendly API.
Best for: E-commerce businesses with strong technical teams.
Describes itself as a payment orchestration platform, offering a single-API connection to 25+ banks and payment institutions, virtual and physical POS, SoftPOS and payment links.
Best for: Businesses managing online and physical channels together.
A payment platform offering virtual POS, payment links, QR in-store payments and B2B dealer collections; it states that it routes transactions to the lowest-commission POS based on the card's bank.
Best for: Businesses collecting via links and QR.
Describes itself as a payment orchestration platform, offering a single panel for multiple virtual POS accounts, rerouting during POS outages and dealer management.
Best for: Businesses that want to monitor several virtual POS accounts from one panel.
Describes itself as a payment orchestration platform rather than a licensed payment institution, offering smart routing, failed-payment recovery, volume balancing across POS accounts and recurring payment tools.
Best for: Businesses that want to build their payment flow with modular tools.
Payment institutions licensed by the Central Bank of the Republic of Türkiye let businesses accept payments on their own infrastructure. They offer the fastest start, while payment traffic flows through a single channel. They can also be connected to an orchestration platform such as Treps as channels. What is a payment institution?
iyzico, part of PayU, is one of Turkey's best-known payment institutions; it is e-commerce focused and offers a quick start.
Best for: Small and mid-sized e-commerce businesses.
A payment institution known for virtual POS and pay-by-link solutions aimed at SMEs.
Best for: SMEs that want to start quickly.
Paratika, part of Payten (Asseco SEE), offers payment infrastructure focused on enterprise customers.
Best for: Enterprise and large retail businesses.
The business signs a merchant agreement directly with a bank. At high volume this allows direct negotiation, but each bank requires a separate integration and instalment options are limited to the bank's own cards. If you use several bank virtual POS accounts, you can combine them into one integration with Treps. What is a virtual POS?
| Option | Type | Highlights | Best for |
|---|---|---|---|
| Treps | Payment orchestration | 56+ banks and payment institutions, Commission Saver, failover, PCI DSS Level 1, reconciliation, B2B, marketplace, wallet | Mid-large, multi-bank setups |
| Craftgate | Payment orchestration | Multi-PSP routing, developer-friendly API | Tech-heavy e-commerce |
| Finekstra | Payment orchestration | 25+ banks and payment institutions, SoftPOS | Online + physical channels |
| Tahsilat.com | Payment platform | Links, QR, dealer collections | Link and QR collections |
| Payfoni | Payment orchestration | Multi virtual POS panel, dealer management | Single-panel needs |
| Paywall | Payment orchestration | Modular routing and recovery tools | Modular setups |
| iyzico | Payment institution | Quick start, e-commerce focus | SME and mid-size e-commerce |
| PayTR | Payment institution | Virtual POS, pay-by-link | SMEs |
| Paratika | Payment infrastructure | Enterprise focus | Enterprise |
| Bank virtual POS | Direct bank | Direct negotiation with the bank | Single-bank businesses |
Related reading: Payment Gateway Comparison 2026, iyzico Alternatives 2026, How to Reduce Virtual POS Commission Rates
For virtual POS, payment orchestration and integration needs, let our expert team guide you to the best solution.
iyzico, PayTR, Craftgate or Treps — what's the right payment infrastructure for your business? We compare the PSP and payment orchestration models ope...
Read More →
Looking for an iyzico alternative? We break down two distinct categories — other PSPs and payment orchestration platforms — and explain which fits you...
Read More →
Payment gateway, PSP or payment orchestration — what does your business actually need? A complete guide to payment infrastructure concepts and Turkey'...
Read More →