What Is Chargeback Management? How Merchants Can Protect Against Disputes
When a cardholder disputes a transaction with their bank, merchants face both financial and operational risk. We break down how the chargeback process...
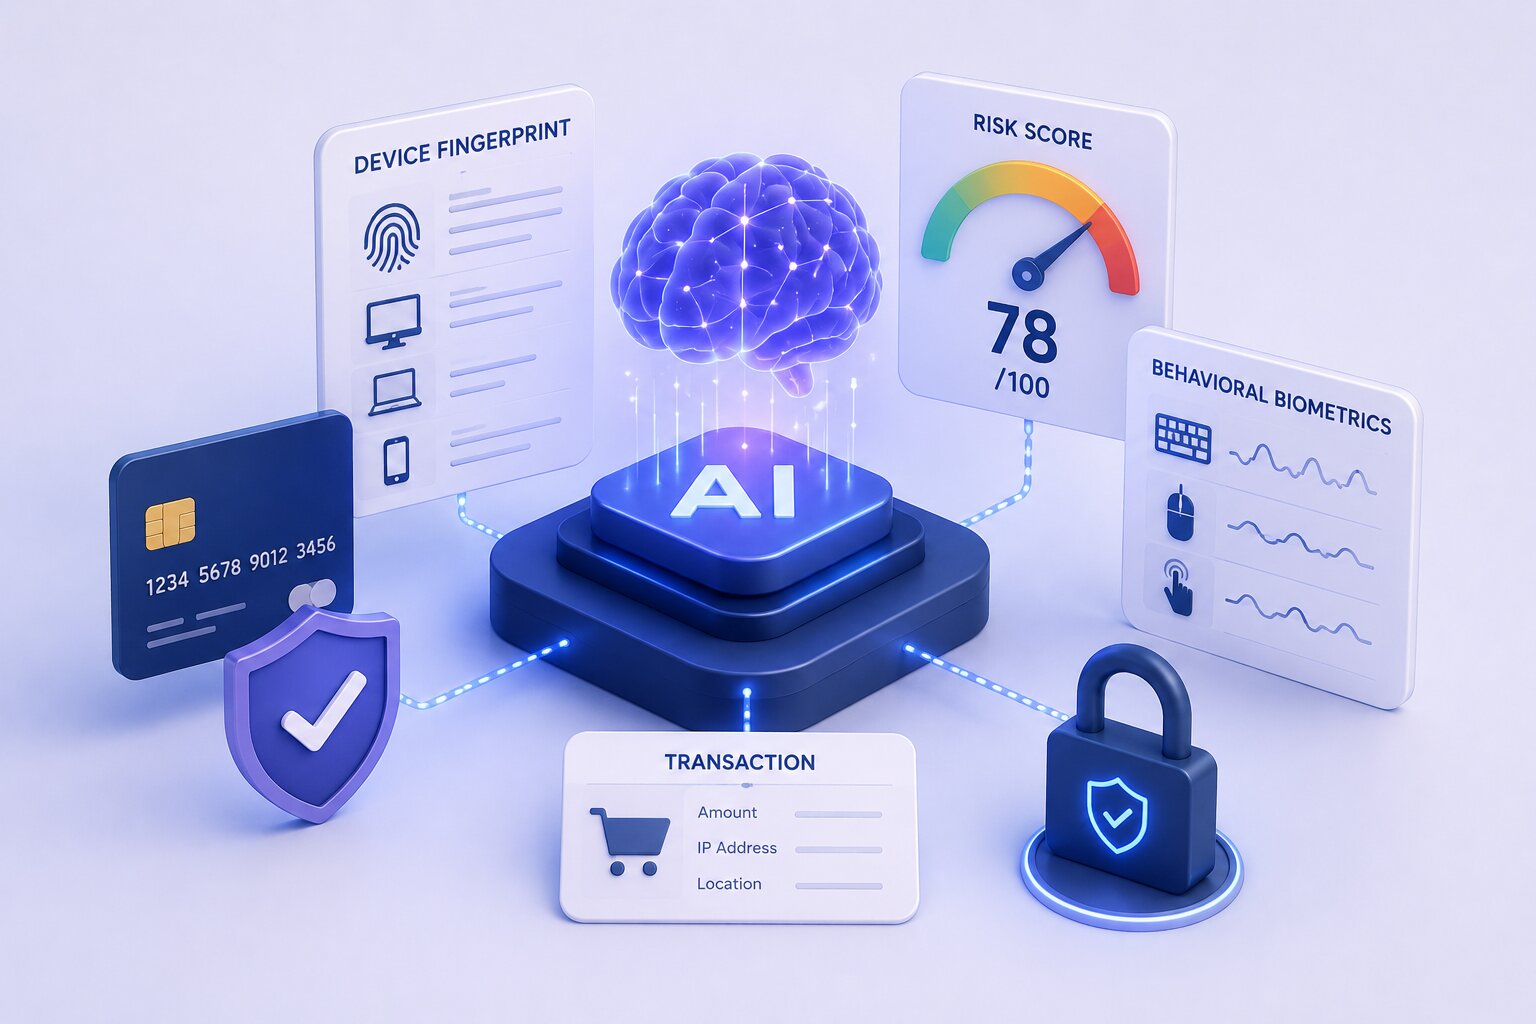
Read More →Rule-based fraud systems are no longer enough. We explain how machine learning models use device fingerprinting, behavioural biometrics, and real-time risk scoring to catch fraud — and how this connects with payment orchestration.
Fraud techniques grow more sophisticated every year — stolen card data, social engineering, botnet-driven card testing attacks, and account takeover are all straining classic rule-based systems. As a result, fraud detection in payments has shifted rapidly toward machine learning (ML) based models in recent years.
Traditional fraud systems rely on static rules such as "flag any single transaction above a threshold", "block more than a set number of attempts in 24 hours", or "flag cards from a specific country". These rules are simple and explainable, but they have two fundamental weaknesses: fraudsters learn to work around them, and they can incorrectly reject legitimate but unusual customer behaviour — such as a customer transacting while travelling abroad (a false positive).
Supervised models learn from millions of historically labelled fraud transactions to generate a risk score for new transactions. Anomaly detection models, on the other hand, require no labelled data — they flag deviations from a user's or merchant's "normal" behaviour pattern, making them particularly effective at catching new, previously unseen fraud patterns.
Every transaction is converted into a risk score, typically 0–100, within milliseconds. Low-risk transactions are approved automatically, high-risk ones are declined, and transactions in the grey zone trigger step-up authentication via 3D Secure. PSD2's risk-based authentication (RBA) exemptions are also managed through this scoring layer.
An overly strict fraud model rejects a share of legitimate transactions too, directly reducing revenue. Balancing fraud losses against false-decline losses requires ML models to be continuously retrained and to operate with merchant-specific, adjustable thresholds.
Fraud detection alone isn't enough — it gains real value when paired with smart routing. For example, a transaction declined on one channel for technical rather than fraud reasons can be rerouted to an alternative channel by the orchestration layer while preserving its risk signal. This optimises both approval rate and security at the same time.
AI-powered fraud detection doesn't replace rule-based systems so much as it complements them with a real-time, continuously learning layer. Applied correctly, it reduces fraud losses while protecting the experience of legitimate customers. Treps's payment orchestration infrastructure combines fraud signals with smart routing to manage this balance on merchants' behalf.
Related reading: EMV 3D Secure and Smart Payment Routing.
For virtual POS, payment orchestration and integration needs, let our expert team guide you to the best solution.
When a cardholder disputes a transaction with their bank, merchants face both financial and operational risk. We break down how the chargeback process...
Read More →
EMV 3D Secure (3DS 2.0) has been one of the most comprehensive protocols developed to secure card payments since 2016. Yet many PSPs, banks and mercha...
Read More →
With the advancement of technology, the way we pay for goods and services has changed significantly. Pay by Link Payment allows customers to make paym...
Read More →